Canadian Lumber Output Drops 8.6% in 2026 as US Demand Slows
Canadian sawmills cut lumber output 8.6% in 2026, yet Western SPF prices face Q4 downside as US residential construction cools. See procurement tactics.
Statistics Canada reported that domestic sawmills sharply curtailed lumber production as persistent demand weakness forced operational pullbacks across Canadian wood producers. Sawmill output dropped 8.6% month-over-month to 3,546,400 m³ in July 2026, while U.S. residential building payrolls shed 4,900 jobs in September. Maintain lean 10 to 14-day inventories and push for $10 to $15 discounts below print on prompt SP…
LumberFlow Procurement
Put this market signal into the buy-side workflow it informs.
Impact on Your Procurement Strategy
Statistics Canada confirmed that Canadian sawmills curtailed operations sharply in mid-summer, with July 2026 lumber production falling 8.6% month-over-month to 3,546,400 m³, representing a 6.7% decline compared to July 2025. Sawmill shipments contracted even faster, sliding 10.3% from June to 3,728,900 m³. CME lumber physical futures reflected this ongoing weakness, drifting down to $523.50 per mfbm on October 5, 2026, marking an 8.31% drop across the previous four weeks. Despite widespread Canadian mill curtailments, cash markets continue to soften because downstream U.S. consumption is eroding at an even faster pace than Canadian mill curtailments can absorb.
Underlying housing indicators explain why supply cuts have failed to ignite a price rally. Redfin reported that 21.1% of active U.S. residential listings underwent price cuts during the four weeks ending September 20, 2026, matching the highest share for this seasonal window since 2018. Price reductions are concentrated heavily across former pandemic boom markets, led by Denver at 30.9%, Indianapolis at 29.9%, San Antonio at 26.8%, Dallas at 26.6%, and Austin at 26.1%, where active sellers outnumber active buyers by more than two to one. With benchmark 30-year fixed mortgage rates lingering above 7.0%, homebuilders have slowed project groundbreakings. Bureau of Labor Statistics payroll data analyzed by the NAHB reveals that residential building and trade contractors shed 4,900 jobs in September 2026, even as total construction employment grew by 11,000 positions on the back of commercial projects. For an in-depth framework on tracking these macro shifts, examine how housing starts and lumber demand drive mill order files.
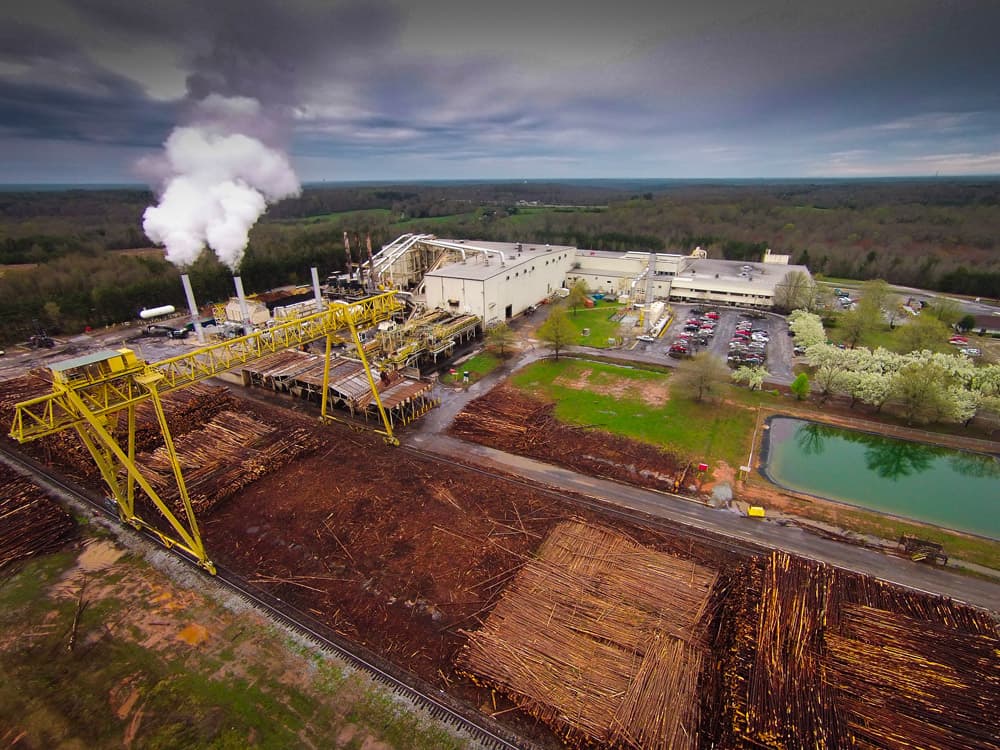
On the manufacturing side, Canadian lumber producers face severe margin compression from high log costs, timber tenure constraints in British Columbia, and compounding U.S. trade duties. Canadian softwood lumber exports to the U.S. fell 12% year-over-year in the first half of 2026, representing a loss of 1.73 million m³ in cross-border volume. Softwood producers face combined anti-dumping and countervailing duty deposits of 35.16%, in addition to a 10% border tariff. In testimony before the Senate of Canada on October 5, 2026, the Forest Products Association of Canada (FPAC) noted that 5 Canadian sawmills have permanently closed this year. However, because U.S. retail yard turnover has slowed, prompt mill order files for 2x4 and 2x6 Western SPF studs and dimension lumber remain compressed at 1 to 2 weeks, eliminating any supply squeeze that might otherwise emerge from mill closures.
Rail transit and delivery timelines further reinforce this buyer's market. Class I carriers, including Canadian National and Canadian Pacific Kansas City, report average dwell times below 24 hours at major western interchanges, allowing Western SPF carloads to reach Upper Midwest reloads within 10 to 14 days of order placement. Southern Pine sawmills across the U.S. South continue to operate with ample supply, keeping Eastern and Central buyers from bidding up Western carloads. With substitute species trading at parity and southern yellow pine 2x4 #2 holding near $390 per MBF mill, Canadian dimension sellers have virtually no pricing leverage to enforce published print lists when booking mixed cars or volume blocks.
These market dynamics require building material distributors to adjust both sales targeting and inventory control. Distributor sales managers should redirect field reps toward commercial framing, multifamily sub-trades, and municipal infrastructure projects, targeting sectors that contributed to the 16,100 nonresidential construction jobs created in September 2026. On the procurement desk, buyers should maintain an aggressive just-in-time posture, capping yard framing stock at 10 to 14 days of supply and bidding $10 to $15 per MBF below print on prompt carloads, as mills remain eager to keep tallies moving.
Looking ahead through Q4 2026, lumber pricing remains in a downward drift, with benchmark cash indices softening by roughly 2% over three weeks in a low-volatility trading band. Quantitative projections point toward an additional 2.2% price decline over the coming week, giving procurement teams little incentive to take on speculative price risk. Buyers monitoring the core factors affecting lumber prices should continue relying on steady replacement purchasing, letting mills hold unsold inventory until mortgage rates ease and single-family starts stabilize.
Key Takeaways
Canadian July sawmill output fell 8.6% to 3.55M m³, but persistent U.S. demand destruction continues to outpace Canadian mill curtailments.
Over 21.1% of U.S. home sellers cut asking prices as mortgage rates stay above 7%, driving residential building payrolls down 4,900 jobs.
Cap dimensional framing inventory at 10-14 days of forward cover and secure $10-$15/MBF discounts on prompt Western SPF dimension.
Market Outlook
Pricing Trend: DOWN
Confidence Level: MEDIUM
Recommended Action: Cap framing inventory at 10 to 14 days of forward supply and secure $10 to $15 per MBF discounts below print on prompt SPF carloads before booking Q4 replenishment.
Why are Western SPF lumber prices falling despite Canadian sawmill closures in 2026?
Although Canadian sawmill production dropped 8.6% in July 2026 and 5 mills have permanently shut down, U.S. single-family building demand has softened even faster. With residential construction losing 4,900 jobs in September and mortgage rates stuck above 7.0%, distributor takeaway is too sluggish to absorb current mill capacity.
How should lumberyards manage framing inventory through Q4 2026?
Distributors should avoid speculative forward buys and maintain a lean 10 to 14-day supply on ground. Because mill order files are short with lead times of just 1 to 2 weeks, buyers have leverage to negotiate discounts of $10 to $15 per MBF below print on replacement tallies.
How LumberFlow Helps
Find the next project. Make the right buy. LumberFlow is lumber software for sales and procurement.
Sales — LumberFlow Radar (Private Beta). Know which local construction projects to call on next. Radar ranks supported municipal permit activity into a daily project queue your outside reps review, claim, and disposition, with visible reason codes behind every ranking. The same public building activity behind this data is visible to every dealer in your territory right now — Radar turns it into a daily queue your reps can act on before someone else does.
Any territory: build your own prioritized call list with the free lead-prioritization field guide. Radar is live in markets across Nebraska, Ohio, Texas, and Washington. Activation is by invitation — request an activation invite and tell us where your team sells.
Buying — LumberFlow Procurement. Use the weekly price forecast to identify turning points before committing capital, and monitor shifting mill dynamics through our free daily market insights. Sourcing teams working inside LumberFlow can use automated sentiment alerts at the requisition level to capture $10 to $15 per MBF in supplier concessions. Book a 20-minute demo of the separate buy-side product.
RFQ command center
Turn supplier emails into a buying board
LumberFlow reads supplier emails, extracts quote details, and keeps buyer approval on every RFQ, counter, award, and PO.
Related Insights
Continue exploring lumber market analysis
Use this signal where buying decisions happen
LumberFlow puts market context beside active RFQs, quote economics, and follow-ups your buyer can approve.
Need help applying this insight?
Talk with a LumberFlow analyst about procurement playbooks tailored to your SPF program.